$300B
of assets monitored across deployments

Credit risk suite
Continuously monitor credit portfolios to detect stress, fraud, and emerging risks before losses grow.
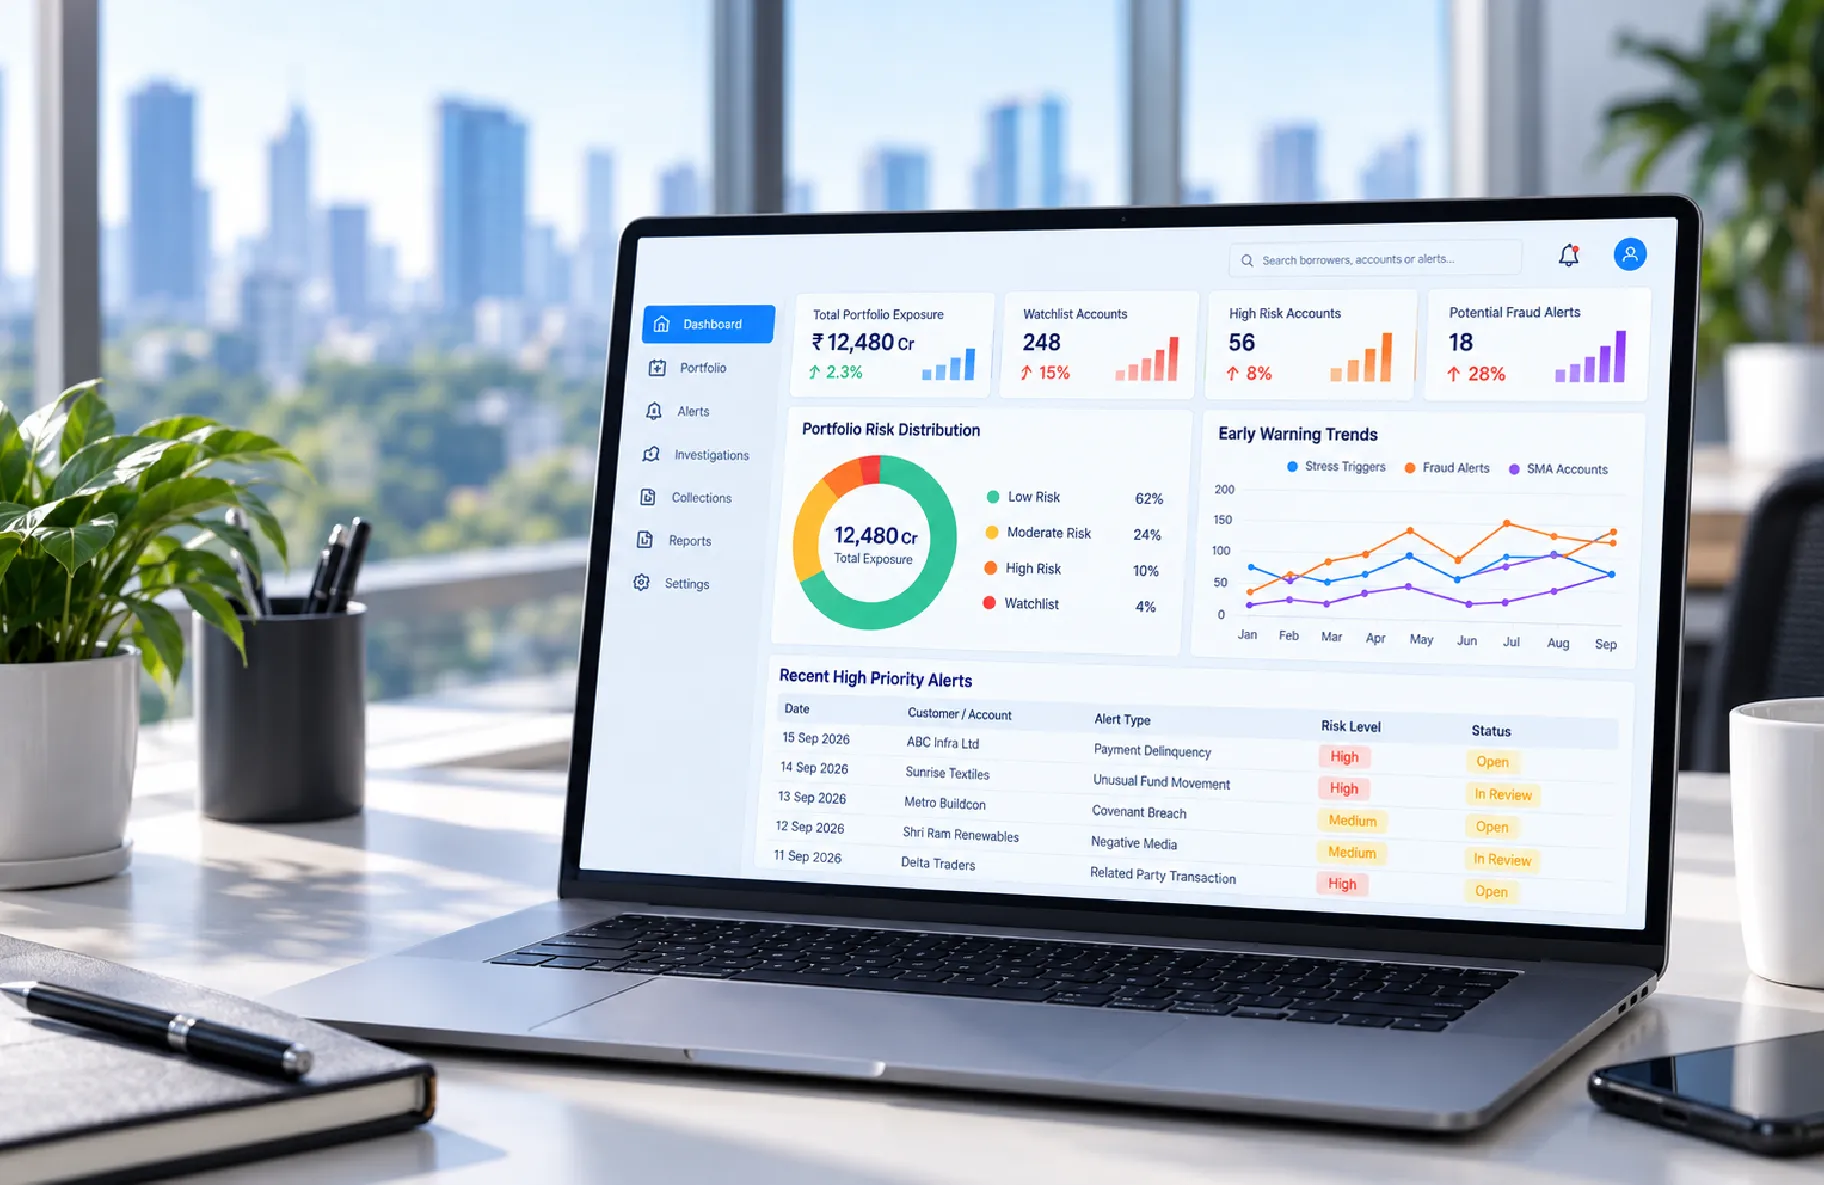
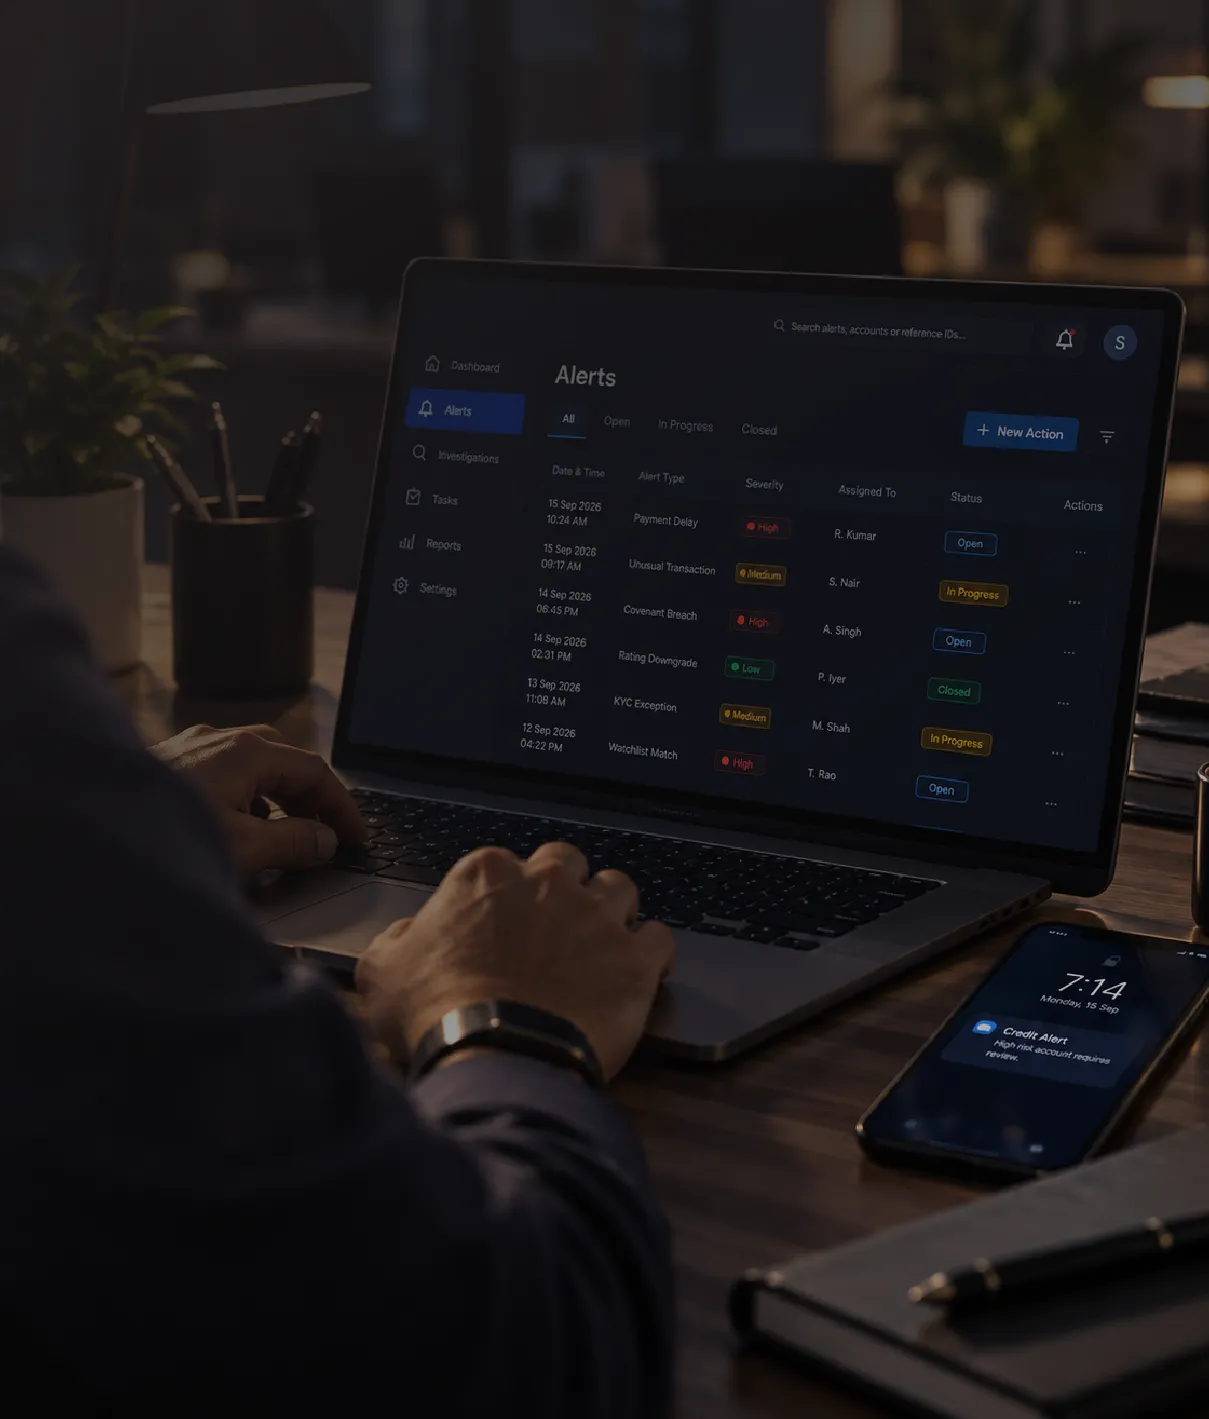
rt360 gives banks, NBFCs and lenders a continuous view of borrower risk. It brings together core banking, ratings, bureau, market and media data across the loan lifecycle to detect early signs of credit stress and fraud. By correlating signals to a single borrower, rt360 scores risk, alerts a named owner, and drives action from investigation through collection and recovery. Teams act before losses escalate.
Explore the business impact of continuous credit risk monitoring.
$300B
of assets monitored across deployments
9
countries in one multi‑country rollout
4
modules across the credit lifecycle
Periodic reviews catch deterioration late. rt360 continuously monitors triggers, enabling action when risk events occur.
Core banking, ratings, bureau and market data sit apart. rt360 connects them into one complete borrower risk view.
Traditional systems miss advances-related fraud. rt360 monitors credit, staff, office and suspense accounts in real time.
Unassigned alerts go unresolved. rt360 routes every trigger to the right owner with reminders, escalations and closure tracking.
Growing loan books overwhelm manual review. rt360 automates high-volume monitoring and sends only material exceptions to teams.
Fragmented data makes timely red flag and SMA identification difficult. rt360 automates detection and supporting regulatory reports.
From data integration and early warnings to fraud detection, scoring, collections and pricing, rt360 connects every capability needed to manage credit risk end to end.
Connect banking, ratings, bureau, market and external data sources in real time, near real time or batch for a unified borrower view.
Detect credit stress across account conduct, delinquency, collateral, covenants, financials and external behaviour with configurable alerts.
Identify fraud, suspicious transactions, anomalies and emerging patterns using rule-based monitoring and supervised or unsupervised models.
Combine internal, external and bureau ratings to calculate risk scores, probability of default, RAROC and risk-based pricing.
Route every alert to the right owner with configurable thresholds, reminders, escalations, reassignment and complete audit trails.
Prioritise overdue accounts by risk and recovery history, then plan, track and measure collection outcomes across branches and teams.
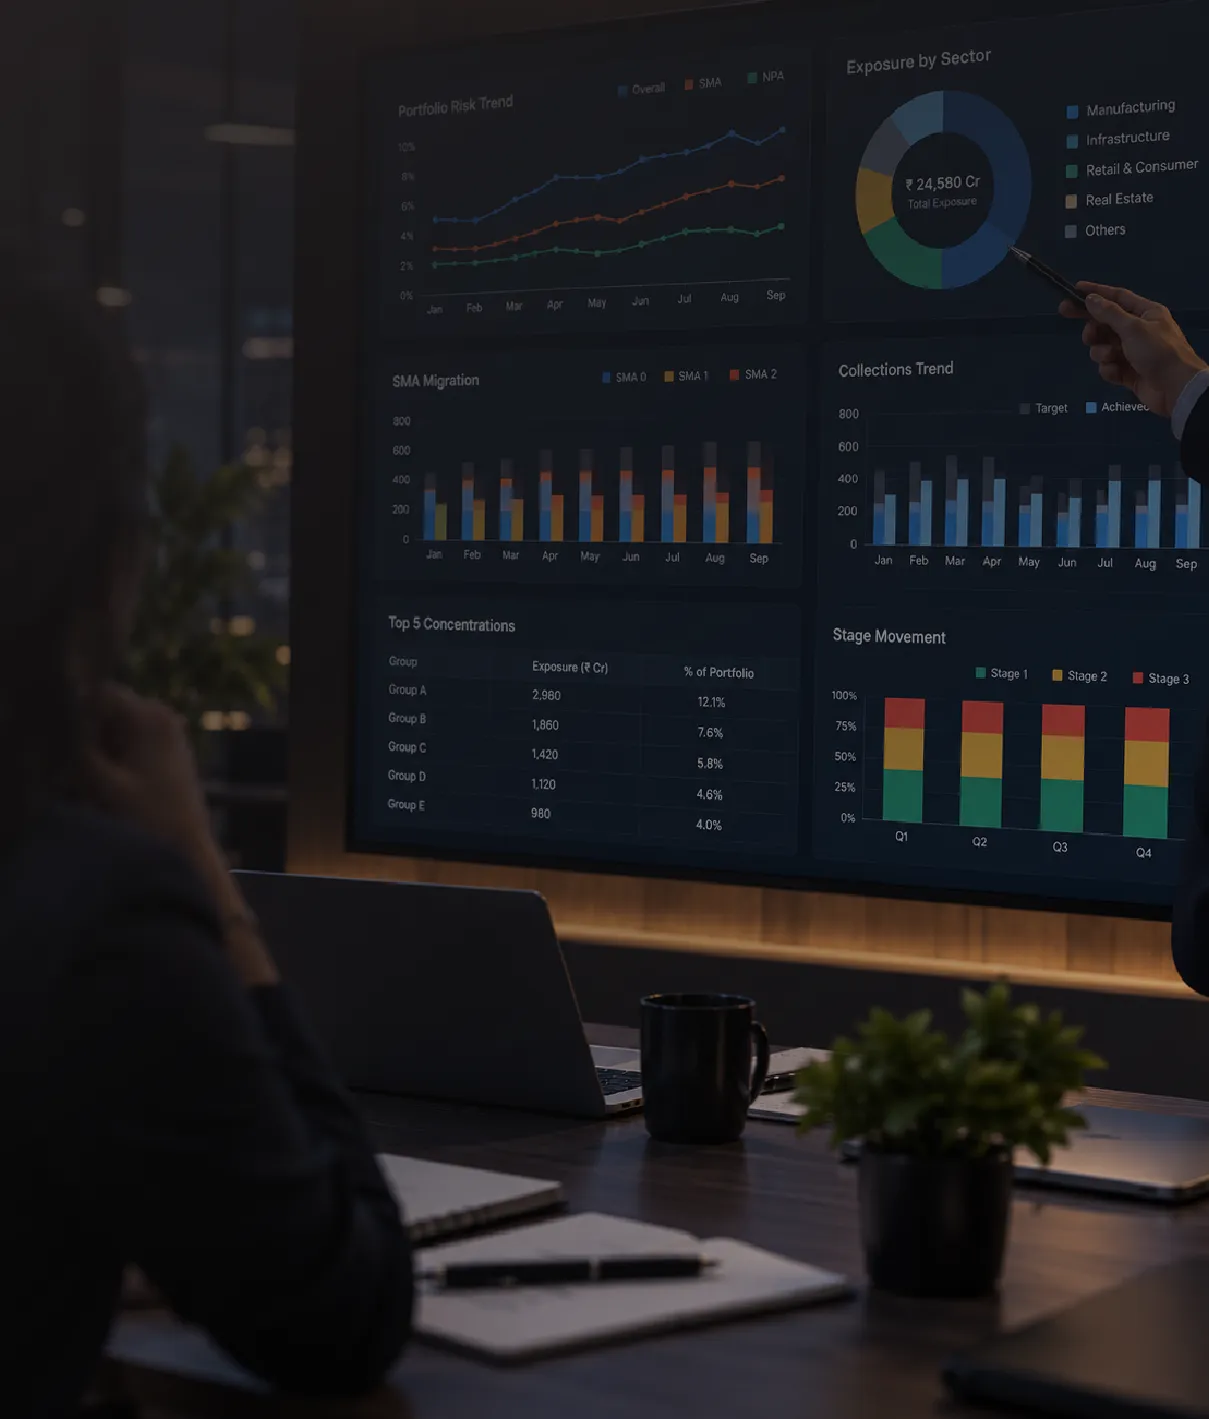
Monitor portfolio risk, delinquency, SMA migration, collection efficiency and customised MIS through actionable 360-degree borrower views.
Push risk outcomes back into banking systems to trigger re-rating, account freezes, origination actions and fraud interventions.
Five stages, running continuously rather than at review dates:
Data arrives from internal and external sources in real time, near real time or batch, then passes through cleansing, transformation, reconciliation, privacy and governance controls.
The credit monitoring engine applies regulatory triggers, custom bank rules and machine-learning models across retail, SME and wholesale lending, operations and transactions.
Internal and external ratings, bureau scores, delinquency history and live alerts combine to produce risk scores, default probabilities, distance to default and risk buckets.
Configurable workflows route alerts to the right officer with thresholds, reminders and escalations, supported by email, SMS, dashboards, customer views and audit trails.
Outcomes return to the bank's systems: re-rating, account freezes, feedback to origination on stressed loan products, and action on channels or branches showing high fraud rates.
Early warning triggers use traffic-light thresholds to focus credit officers on material risks, not event volume.
Email and SMS alerts, FYI notifications, reminders, escalations, mass actions, reassignment and mandatory closure by authorised users.
Track portfolio risk, delinquency, roll rates, SMA migration, concentration, restructuring, stage movement and collections, with borrower-level drill-down.

Enterprise-wide monitoring across corporate, retail and MSME portfolios, branches and users, including fraud.

Monitor beyond core banking with delinquency, collateral, insurance and bureau data in one view.

Multi-tenant architecture with data localisation, proven across nine countries from one deployment.

Monitor beyond core banking with delinquency, collateral, insurance and bureau data in one view.
Connect core banking, data lakes, bureaus, HRMS, IVR, gateways and unstructured data through batch uploads.
Run real-time transaction monitoring and batch portfolio analytics on one platform, at the frequency each use case needs.
Cleanse, transform, reconcile and govern incoming data before it reaches the monitoring engine.
Configure rules, thresholds, workflows and approval hierarchies to match each institution's credit policy.
Financial institutions choose BCT because it is:
Credit risk is monitored continuously, not at review points, with an always-on architecture built around live data rather than periodic review cycles.
Most institutions separate credit and fraud monitoring, leaving advances fraud exposed. rt360 covers both through one unified borrower view.
Detection is only the start: scoring, workflow, collections prioritisation and outreach connect every signal to a recovery action, from alert to recovery.
Outcomes feed back into ratings, account status, origination and channel management, closing the loop that monitoring tools leave open.
Validated by regulatory sandbox, listed on Azure Commercial Marketplace and recognised by Chartis, reinforcing rt360's market credibility.
From early warning to recovery, rt360 brings together four connected modules that help lenders detect risk, act decisively and protect returns.
| Module | What it does | Why it matters |
|---|---|---|
| Early Warning System (EWS) | Aggregates internal and external data to flag credit stress with predictive scoring and covenant, collateral and document monitoring. | Intervention becomes possible before default, not after |
| Real Time Monitoring System (RTMS) | Scans transactions in real time to detect fraud, fund diversion, KYC/AML exceptions, mule accounts and account takeover. | Extends fraud monitoring to advances, where traditional systems do not reach |
| Collections Management System (CMS) | Prioritises overdue accounts, automates follow-up and payment outreach, and tracks collection efficiency across teams. | Turns an alert into a recovery action instead of a report |
| RAROC Calculator | Calculates risk-adjusted returns, supports break-even pricing to hurdle rates, and streamlines credit approval decisions. | Prices risk correctly at the point it is taken on |
Discover how rt360 helps financial institutions transform credit risk into smarter, more proactive lending.
Tell us about your portfolio and systems, and we'll show how rt360 detects, scores, routes and closes critical credit exceptions.
rt360 Credit Risk Suite is a credit risk monitoring platform for banks, NBFCs and other lenders. It integrates internal and external data across the loan lifecycle, detects early warning signals of credit stress and fraud, scores borrower risk, and drives the workflow from alert to action to collection.
rt360 is built for banks, NBFCs, housing finance companies and other financial institutions including leasing companies and fund houses managing private credit. Its primary users are chief risk officers, chief credit officers and heads of credit, along with credit monitoring, fraud, collections and risk teams.
An early warning system is an automated method of identifying credit risk at an early stage. It aggregates data from internal bank systems and external public sources, then raises indicators of possible credit distress or fraud so lenders can intervene before default rather than after it.
Internally: core banking, transactional systems, ratings, LOS and LMS, fraud risk systems, transaction monitoring, suspicious transaction lists and document management. Externally: credit bureaus, corporate databases, central bank databases, market and macroeconomic data, external ratings, financial data, adverse news and litigation data.
A base score is built from internal ratings, external ratings and credit bureau scores where available. That score is then adjusted for delinquency history and for live early warning alerts, producing an EWS risk score, probability of default, distance to default and a risk bucket from very low to very high.
Yes. Alongside credit monitoring, rt360 monitors suspicious transactions and fraud indicators including fund diversion, end-use of funds, KYC and AML exceptions, money mule patterns, account takeover indicators, transactions with restricted entities, and activity in staff, office and suspense accounts.
Yes, alongside rule-based triggers. Supervised models are used where enough labelled outcomes exist to train on, and unsupervised techniques including Isolation Forest, DBScan and Local Outlier Factor detect anomalies without prior labelling. These were chosen over neural networks for lower computational cost and memory use.
Each alert travels a configurable path across offices, departments and hierarchy levels defined by the bank at alert level. Granular thresholds control what is raised, a traffic-light view shows severity, auto-reminders and escalations chase it, and the alert must be closed by an appropriate user with an audit trail.
Yes. The Collections Management System prioritises overdue accounts by risk bucket, days past due, external data and self-cure history, supports account-level planning and target tracking, automates email, SMS and IVR outreach with embedded payment links, and reports collection efficiency and SMA migration.
Book a demo. Share the portfolios you monitor, the systems your credit and transaction data sits in, and where follow-up currently breaks down. The team will map which modules apply — early warning, real-time monitoring, collections or risk-based pricing — and what integration would involve.